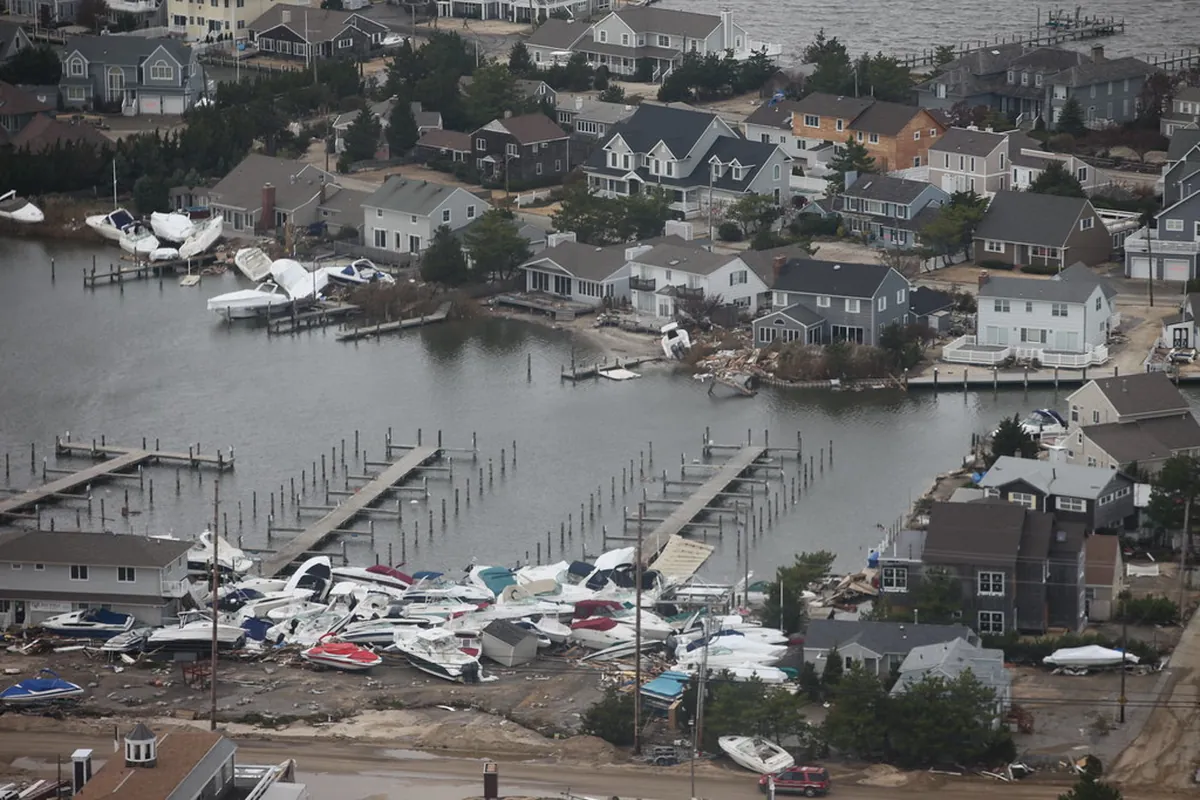
When Sandy came ashore in October 2012, thousands of New Jersey homes were damaged by wind and by surge in the same night. Many owners found that the hardest part of the claim was deciding which policy paid for what.
Two policies, two sets of rules
Homeowners policies cover wind but exclude flood. Flood insurance, usually through the National Flood Insurance Program, covers flood but not wind. Each has its own deductibles, limits, deadlines and claim process.
How to document a mixed loss
- Mark the water line inside and outside, with photos and measurements.
- Photograph the roof, windows and siding before any repairs or tarping.
- Note the order of damage. Was the roof open before the surge arrived? Neighbors, weather records and timestamps can help.
- Keep the two claims separate on paper, room by room and item by item.
Where disputes start
Interior damage above the water line, elevated-home stairs and decks, and mold that grew after the storm are the items most often pushed from one policy to the other. Careful documentation is the best protection.
Where appraisal fits
A homeowners appraisal panel values the covered wind damage. It doesn’t decide the flood claim, and causation disputes may need legal advice.