- Coastal storms
- Wildfire smoke
- Wind
- Tree fall
- Frozen pipes
From the barrier island to the pines
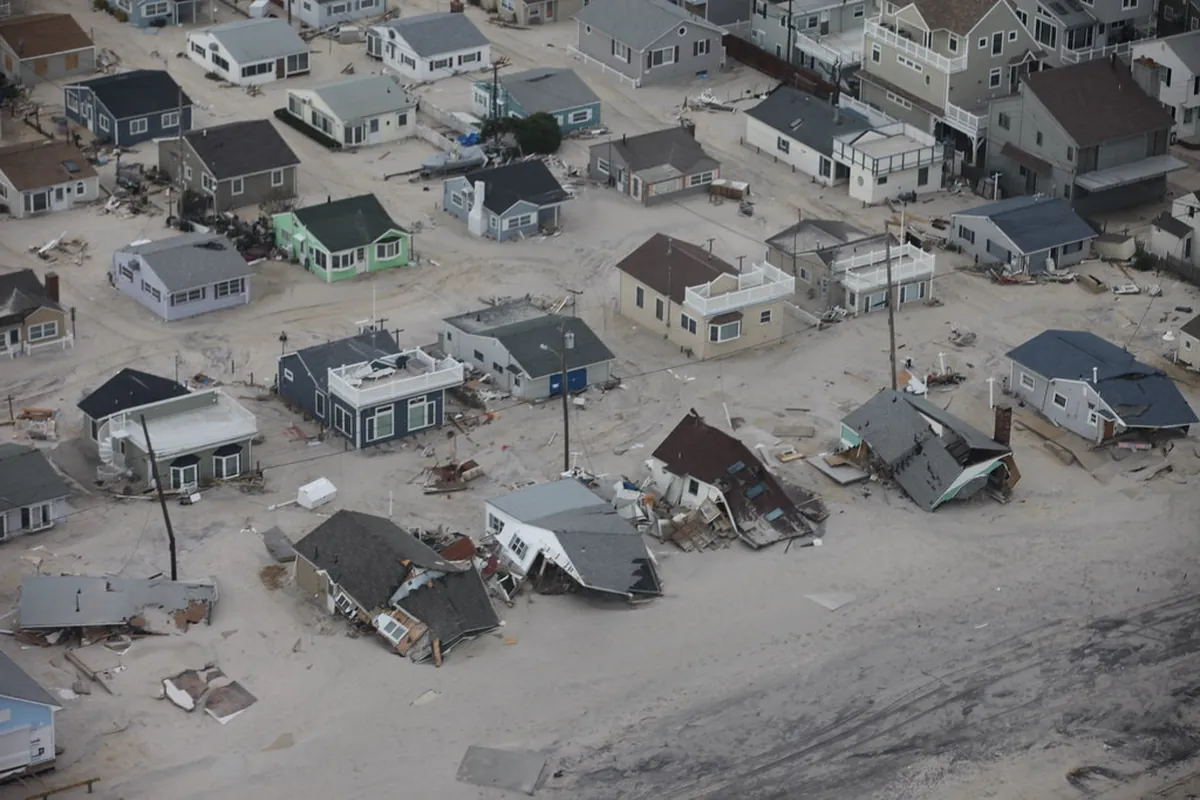
Toms River covers about 50 square miles. Ortley Beach, on the barrier island, was one of the hardest-hit communities in the state when Sandy came ashore in 2012; many homes there have since been rebuilt or raised. On the mainland, neighborhoods like Silverton, Gilford Park and the areas along Barnegat Bay have capes, ranches and bayfront bungalows. North Dover and the western sections back up to pine forest.
Two very different risks
Coastal storms bring wind, wind-driven rain and surge, which means homeowners and flood claims often overlap. Inland, the Pinelands bring wildfire risk. The 2007 Warren Grove fire and the 2025 Jones Road Wildfire both burned large areas of Ocean County and sent smoke into nearby neighborhoods.
Disputes we see in Toms River
- Wind and flood damage on the same home, split unevenly between policies.
- Elevated homes with stairs, decks and utilities left out of the scope.
- Smoke damage from wildfire dismissed because the house didn’t burn.
- Roof and siding damage from nor’easters.
We serve Toms River and nearby Ocean County communities, including Brick, Lakewood, Berkeley, Lacey, Manchester, Seaside Heights and Island Heights.
Services available in Toms River
Every New Jersey Insurance Appraiser service is available to property owners in Toms River and the rest of Ocean County, including:
- Appraisal Demand Representation
- Homeowners Insurance Appraisal
- Condo, HOA & Commercial Appraisal
- Roof & Hail Damage Appraisal
- Wind & Tornado Damage Appraisal
- Hurricane & Nor’easter Claim Appraisal
- Water, Ice Dam & Pipe Burst Appraisal
Questions from Toms River property owners
My shore home was damaged by wind and storm surge. How do the claims work?
Usually as two claims: flood damage under a flood policy and wind damage under the homeowners policy. Documenting what was damaged by each cause is the key.
Wildfire smoke got into my home during an evacuation. Is that covered?
Smoke damage is commonly covered under homeowners policies. The question is usually how much cleaning or replacement is needed.