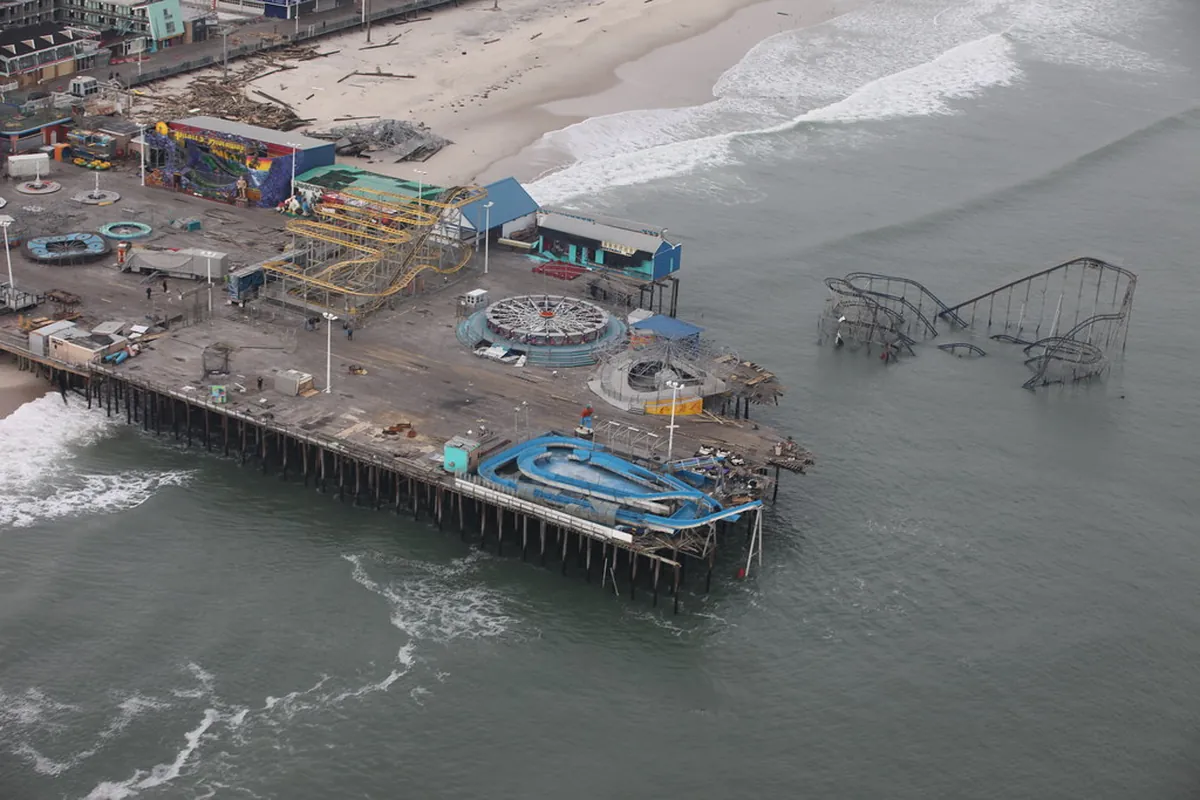
Storms that set the pattern
The Ash Wednesday Storm of March 1962 battered the shore for days. Hurricane Irene came ashore near Little Egg Inlet in August 2011 and flooded inland river towns. Superstorm Sandy made landfall near Brigantine on October 29, 2012, pushing record surge into Monmouth, Ocean and Hudson counties and changing the shore for good. Nor’easters keep coming every winter, including the Halloween snowstorm of 2011 and four in three weeks in March 2018.
Hurricane deductibles in New Jersey
Many New Jersey homeowners policies carry a hurricane or named-storm deductible, often a percentage of the dwelling limit, that applies only when specific trigger language is met. After Sandy, the state told insurers that hurricane deductibles should not apply because the storm was no longer a hurricane at landfall. Your policy’s exact wording decides how a future storm is treated. Read the deductible endorsement on your declarations page, not just the number.
Wind versus water
The hardest coastal claims involve damage from both wind and flood. Homeowners policies generally exclude flood, which is covered separately, usually through the National Flood Insurance Program. Wind-driven rain through a damaged roof or window is usually a homeowners claim. Storm surge through the first floor is usually a flood claim. On the same house, the two blur. We document water lines, the order of damage and roof and window openings so each policy pays its share.
- Interior water damage above the flood line.
- Roof, siding, deck and window damage from sustained wind.
- Elevated-home components, such as stairs and decks, that may sit under either policy.
- Mold that follows a wind opening left unrepaired.
Frequently asked questions
Does my hurricane deductible apply to a nor’easter?
Usually not, unless your policy uses a broader windstorm deductible. Hurricane deductibles typically depend on an official hurricane declaration or warning. Read the trigger language in your endorsement.
Can appraisal decide how much damage was wind and how much was flood?
The homeowners panel values the damage covered under that policy. Where wind and flood overlap, careful documentation of what was damaged by which cause matters a great deal. Coverage disputes about causation may need an attorney.
Who insures shore homes the voluntary market won’t?
The New Jersey Insurance Underwriting Association, the state’s FAIR Plan, offers basic property coverage. Its policies also contain appraisal language, and we work on those claims too.