Wind events that shape New Jersey claims
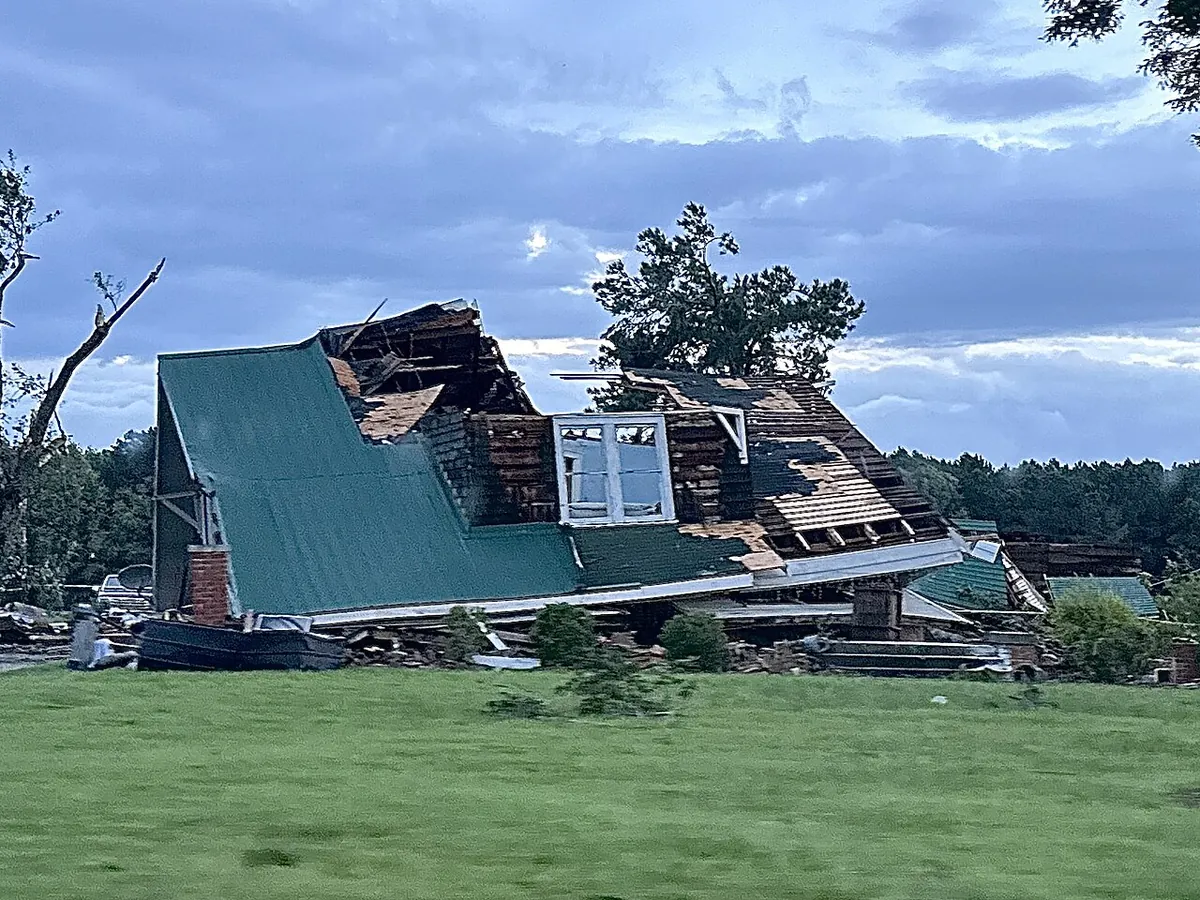
On June 29, 2012, a derecho crossed South Jersey with gusts strong enough to topple trees and peel roofs from Salem County to the shore. On September 1, 2021, the remnants of Hurricane Ida spun up a strong tornado that tore through Mullica Hill in Gloucester County, the most destructive New Jersey tornado in decades. Most wind claims are smaller: a summer squall line or a winter nor’easter that creases shingles and pulls off siding across a neighborhood.
What we look for after wind
- Creased or unsealed shingles that look intact from the ground but no longer resist the next storm.
- Vinyl and aluminum siding that can’t be matched, forcing a decision about whole elevations.
- Fences, sheds, detached garages and pool equipment under other-structures coverage.
- Racked framing, cracked trusses and shifted foundations after a tornado or direct tree strike.
- Interior water damage that followed the wind through an opening.
Repair or replace
Most wind disputes are not about whether the wind happened. They are about how much of the roof or siding must be replaced. We document every damaged course, test whether repairs are feasible and research whether matching materials exist, so the panel decides the question on evidence.
Frequently asked questions
Is a tornado covered under a standard homeowners policy?
Wind damage, including tornado damage, is generally covered under homeowners and commercial property forms, subject to deductibles and exclusions. Flooding that follows a storm is usually excluded and needs separate flood coverage.
The carrier only approved a few shingle repairs. What should I do?
Ask for the basis in writing, photograph every damaged area, and get a contractor’s opinion on repairability. If the gap is large, an estimate review or appraisal may help.
Do you handle fence and shed claims?
Yes, usually as part of the larger claim. On their own, small items rarely justify appraisal fees.