Why the trigger matters in New Jersey
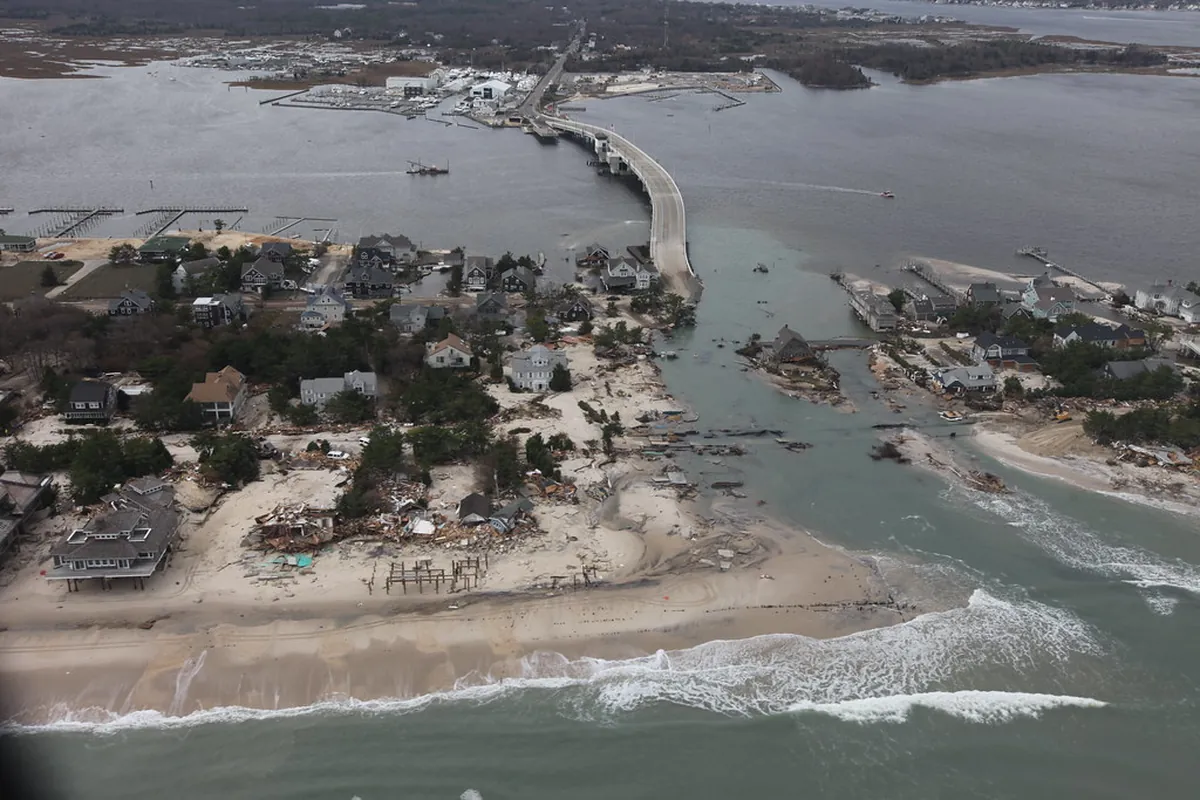
Hurricane deductibles usually apply only when the policy’s trigger language is met, for example a hurricane warning issued for New Jersey or a storm officially classed as a hurricane. After Superstorm Sandy in 2012, the state said hurricane deductibles should not apply because Sandy wasn’t a hurricane when it came ashore. Nor’easters usually fall under the ordinary deductible unless your policy uses a broader windstorm deductible.
Where to find yours
Look on the declarations page for “hurricane,” “windstorm” or “named storm” deductible, then find the endorsement that defines it. Note any minimum dollar amount.
What it means for appraisal
The deductible doesn’t change the amount of loss a panel decides. It changes what you receive. A loss just above the deductible may not be worth disputing. One far above it may be.
Questions about this tool
Does the percentage apply to my contents too?
The percentage is usually calculated from the dwelling limit and then applied to the whole storm loss. Check your policy’s wording.
Can I lower my hurricane deductible?
Sometimes, at renewal, for a higher premium. Coastal homes may have fewer options.