- Flash flooding
- Burst pipes
- Multi-family fires
- Flat-roof leaks
- Wind
Newark’s housing and the claims it produces
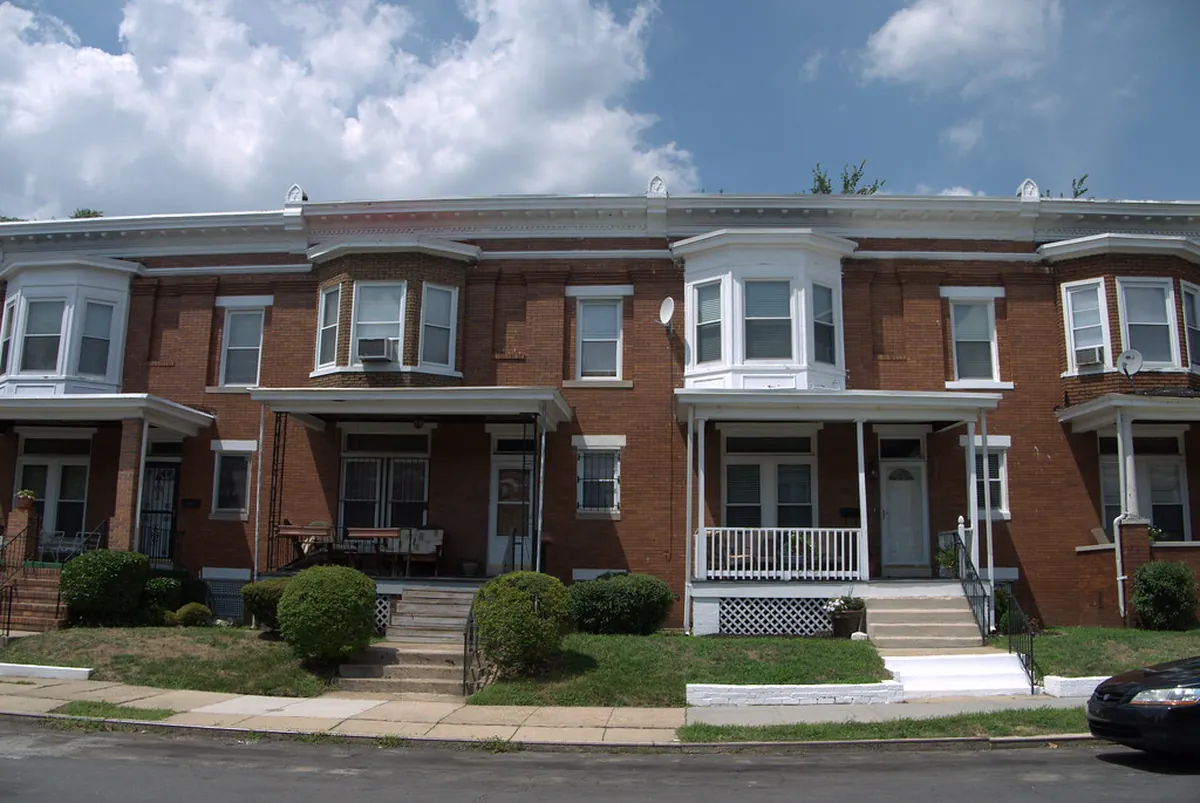
Much of Newark was built between the 1890s and the 1950s. In the Ironbound, narrow frame and brick homes stand shoulder to shoulder, so a fire or roof leak in one often reaches the next. The North Ward and Vailsburg are full of two- and three-family houses with flat or low-slope roofs that pond water after heavy rain. Forest Hill has large early-1900s homes with slate roofs, plaster walls and detailed millwork. Downtown and University Heights add apartment towers and converted commercial buildings.
Storms that hit Newark
Sandy’s surge pushed up the Passaic River and Newark Bay in 2012, flooding parts of the waterfront and Port Newark. In September 2021, Ida’s remnants dropped intense rain on Essex County, flooding basements and streets across the city. Winter brings frozen pipes in older buildings with exterior plumbing runs and boiler systems that strain in cold snaps.
Disputes we see most in Newark
- Low-slope roofs patched on paper when the membrane and insulation need replacement.
- Multi-unit water losses valued as a single unit.
- Plaster interiors priced as drywall.
- Smoke damage in attached homes dismissed as “no direct fire damage.”
- Basement water claims denied as flood or groundwater without checking the source.
We inspect throughout the Ironbound, North Ward, Central Ward, South Ward, Vailsburg, Weequahic, Forest Hill, Roseville and Clinton Hill, and in nearby Essex County towns.
Services available in Newark
Every New Jersey Insurance Appraiser service is available to property owners in Newark and the rest of Essex County, including:
- Appraisal Demand Representation
- Homeowners Insurance Appraisal
- Condo, HOA & Commercial Appraisal
- Roof & Hail Damage Appraisal
- Wind & Tornado Damage Appraisal
- Hurricane & Nor’easter Claim Appraisal
- Water, Ice Dam & Pipe Burst Appraisal
Questions from Newark property owners
My two-family home in Newark has damage in both units. Is that one claim?
Usually one claim under the owner’s policy, with a separate scope for each unit and the shared areas. Tenants’ belongings fall under their own renters policies.
Water came through the basement walls during Ida. Is that covered?
Groundwater and surface water are usually excluded under homeowners policies and fall under flood coverage. Sewer backup may be covered by an endorsement. The source of the water matters, so document it.